Weekly Macro Report
Macro Brief — October 05, 2026
Stagflation's 16-week reign just got a confidence haircut even as the data refuse to cooperate
Parson Tang — October 5, 2026Powered by MARY
Gold jumped $203 in a week, from $3,934 to $4,138, and the engine's confidence in the STAGFLATION label fell to 42.7% from 45.9%. That combination — the single largest move in the entire signal set, against a downgrade in the regime call — is the whole story this week. When the model loses conviction on its own label while the market's oldest inflation hedge reprices violently higher, the honest read is not that the regime changed. It is that the regime call is genuinely in question, and two credible interpretations of the same tape are now in play.
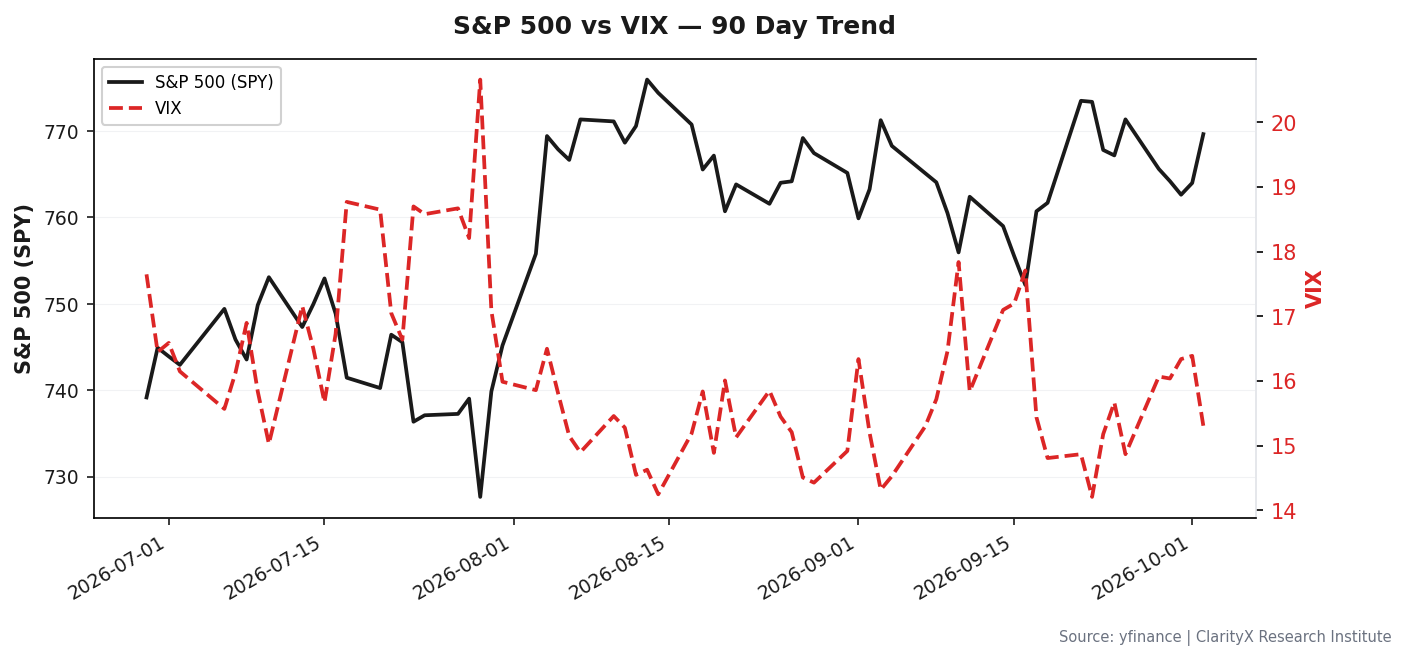 S&P 500 vs VIX — 90 Day Trend
Here is the first read, and it is the one I lean toward. Gold is doing exactly what it should do in a stagflationary regime: CPI sits at 3.71% and core PCE at 3.70%, both unchanged week-over-week, both well above target, while the 10Y breakeven sits at 2.36%. Real yields are flat at 2.87%. If inflation is sticky and the real return on duration is not compensating you for it, gold is the clean expression. The engine's own signal tilt points the same direction: inflation is running 1.7 standard deviations above average, a bearish input, and the recommended book carries 10% gold and 8% commodities — 18% in real assets, funded from the bond sleeve, not from equity.
Here is the second read, and it deserves a fair hearing. Gold at $4,138 with the VIX up only 1.10 points to 15.31, credit spreads at 3.10% on the High-Yield OAS, and NFCI still negative at -0.55 is not a panic bid. It is a debasement bid. That is a different animal. A debasement bid does not require stagflation to be the correct label — it requires only that investors doubt the long end. And the yield curve steepening to a z-score of +2.07, up half a standard deviation in a week, is consistent with exactly that. On this read, the STAGFLATION label is a lagging description and LATE_CYCLE, at 31.8% probability, is the better forward map.
What I will not do is pretend the data resolves this. Consumer confidence fell 3.50 points to 51.70 — that is a real deterioration and it cuts against the benign read. Oil fell $3.34 to $90.18, which cuts against the stagflation read by relieving the input-cost channel. Everything else that matters sat exactly unchanged: claims at 206,000, GDP at 1.50, CPI at 3.71%, PCE at 3.70%, fed funds at 3.63%, the 10Y real yield at 2.87%, unemployment at 4.10%. Nine tracked series, zero movement. When nine inputs are frozen and one asset moves $203, you are watching a repricing of a single variable, not a regime shift.
Where last week's call was wrong: I said the regime's confidence uptrend — five consecutive prints higher, up 5.1 percentage points — was the signal to watch. It broke. Confidence fell 3.2 points to 42.7%, and the five-reading trend is now falling at -0.9%. I also under-weighted the curve. I had been treating the real yield as the transmission channel; the real yield did not move, and the curve steepened half a standard deviation instead. The channel this week was the term structure, not the discount rate level. That is on the record.
The rotation confirms the ambiguity rather than resolving it. Energy, Health Care, and Tech lead; Utilities, Staples, and Real Estate lag. Three leaders, seven laggards, a narrow tape. That is not a defensive rotation — defensives are being sold — but it is not a clean growth rotation either, because the breadth is terrible. Cyclicals-plus-growth leading while bond proxies get sold is what you get when the long end rises, and the 10Y at 5.24%, the 94.8th percentile of its range, says the long end is the pressure point.
The scenario distribution did not move at all. HARD_LANDING at 13.6%, LATE_CYCLE at 31.8%, LIQUIDITY_CRISIS at 22.7%, STAGFLATION at 22.7% — all four exactly unchanged. The model, in other words, is as undecided as I am. Forward risk reads STABLE, with zero critical and zero warning trip wires active, but the stress overlay carries roughly 36% transition mass over three to six months. That is the honest state: no fire, plenty of kindling.
What I'm Doing
The equity anchor holds at 64.4%. Nothing in this week's tape — not a $203 gold move, not a 3.2-point confidence drop, not a curve steepening — is a reason to touch the strategic allocation. What I am doing is tilting within it. The engine's signal work points +4.4% toward equity on the curve signal, and I am expressing that in quality and pricing power rather than in long-duration growth, because the long end is the variable doing the damage. Real-asset ballast stays at 18% combined, funded from the bond sleeve and the international bond sleeve — the domestic bond bucket at 0.1% is too small to fund anything. Cash sits at 7.6% and I am in no hurry to deploy it into a tape this narrow.
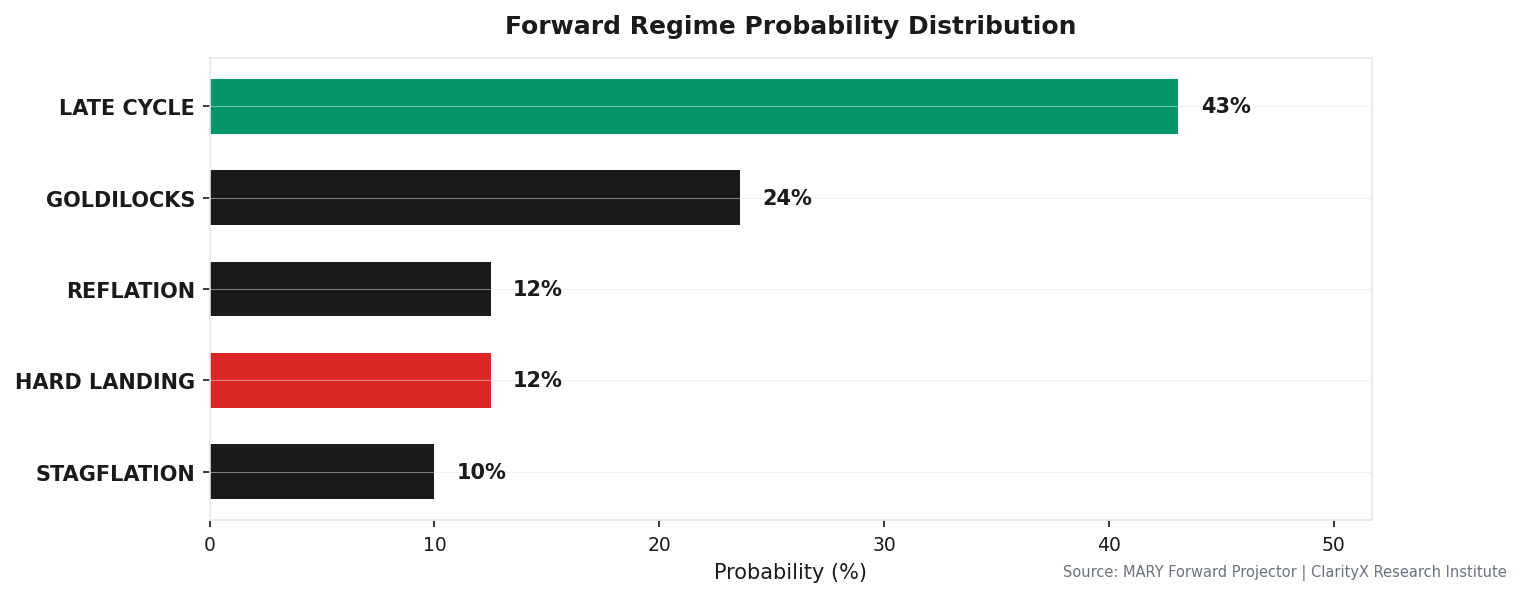 Forward Regime Probability Distribution
What Would Change My Mind
If the VIX crosses 35.0 — currently 56.3% away from that threshold — I do not sell equity. I rotate within it, growth toward low-volatility and quality, and I add to gold and TIPS from the bond sleeve. The anchor is unchanged.
If High-Yield OAS breaks above 5.0% — currently 3.10%, 38.0% away, with no prior reading so the week-over-week change is unknown — the same response applies. That is a credit-stress trigger, and credit stress is funded from bonds, not from the equity anchor. Within equity, the tilt goes to quality balance sheets and pricing power.
If weekly initial jobless claims exceed 236,500 — currently 206,000, 12.9% away and unchanged — that is the labor crack that would make HARD_LANDING the live read rather than a 13.6% tail. The response is a within-equity tilt toward Staples and Health Care and a bond-funded add to TIPS. The equity percentage does not move.
Levels that matter: VIX 15.31 · WTI $90.18 · HY OAS 3.10% · Weekly jobless claims 206,000 · 10Y real yield 2.87% · Gold $4,138
For the full signal dashboard, allocation table, and watch list, see this week's CIO Weekly →
Get this research delivered
New analysis, directly to your inbox. Research notifications only.