CIO Weekly Intelligence Report
CIO Weekly Intelligence Report — September 22, 2026
Late Cycle with Stagflation Conditions — Forward (within-axis): 14% chance conditions rotate toward Goldilocks; elevated
For the analytical argument, read this week's Macro Brief →
The Macro Brief concludes that the anchor holds — but this week the anchor is holding while the engine argues with itself about where it's anchored. Here is the full signal picture and what we're doing about it.
The Verdict
Regime: STAGFLATION | Confidence: 43.9% | Forward Risk: STABLE
Conviction tagline: "Two coordinates, one open question — and the market is priced for neither answer."
Let me state this plainly, because the last two weeks of reports have been read by some of you as a hedge, and it isn't one. This week's regime read is Late Cycle with Stagflation Conditions — one simultaneous read with two coordinates: where we sit in the business cycle, and what growth-and-inflation conditions look like. Both hold at once. They answer different questions. Late Cycle tells you we are late in an expansion that has run a long time; Stagflation tells you the growth-and-inflation mix looks like slow growth with sticky prices. Neither contradicts the other.
The open question is which force dominates from here. Confidence sits at 43.9% — up modestly from 41.3% last week, but still closer to a coin flip than a call. The engine puts 14.3% odds on conditions rotating toward Goldilocks, and roughly 36.4% transition-mass on a stress state (Hard Landing or Liquidity Crisis) within three to six months. The rest is the status quo. When the base case can flip on one print, the posture is not to reposition hard in either direction. It is to hold the anchor, keep the ballast, and let the signal declare itself.
First-time reader? MARY is our 16-signal regime scoring engine. It reads economic data weekly and maps conditions to historical regimes (Goldilocks, Stagflation, Late Cycle, Hard Landing) using 105 economic snapshots from 1990–2026. Confidence = how certain we are of the regime label. Probability = likelihood of a future scenario. Never swap the two.
The Evidence
Oil broke the other way, and that is the story of the week. West Texas Intermediate (WTI) crude sits at $89.74, down from $101.47 six days ago — an 11.6% collapse in one print, and the single largest input change in the dashboard. Last week I wrote that above $100 energy becomes a tax on the consumer and a floor under headline inflation. That floor just dropped. The signal still reads ELEVATED ($80–$100 band), but the direction matters more than the level: a sustained move lower relieves the cost-push pressure that has been the load-bearing wall of the stagflation read. If it holds, the inflation half of the equation weakens and the Goldilocks rotation becomes more than a 14% tail.
Credit is calm — and this week it is very calm. The High-Yield Option-Adjusted Spread (HY OAS) — the extra yield investors demand to hold junk bonds over Treasuries — is 2.68%, tighter by 232 basis points versus the prior week's 5.00% reading. The National Financial Conditions Index (NFCI) reads -0.56, firmly EASY: liquidity is abundant and markets are functioning. The Baa-Treasury spread (investment-grade stress) is 0.94%, also tight. I resolved this same contradiction last week and the resolution has not changed: credit is a coincident indicator, not a leading one. It will be the last thing to crack. Its calm is not evidence against the late-cycle read — it is simply early.
The labor market remains the counterweight. Weekly initial jobless claims came in at 206,000, far from the 236,500 level that would signal real deterioration. Housing permits are weakening — Z-score of -0.62, 1,394k units annualized — and that is the one genuinely late-cycle crack in the data. The yield curve is steepening (Z = +1.00, 10-year minus 3-month spread 0.79pp), which historically is an expansion signal, not a recession one. Taken together: the stagnation half of stagflation is still missing, which is why confidence is 44% and not 70%.
| Signal | Value | vs. Last Week | What It Means |
|---|---|---|---|
| WTI Crude | $89.74 | ↓ -$11.73 (better) | Cost-push pressure easing; the inflation floor just dropped |
| HY OAS | 2.68% | ↓ -232bp (better) | Credit pricing a soft landing; coincident, not leading |
| NFCI | -0.56 | → unchanged | Liquidity abundant; financial conditions very loose |
| Housing permits | Z = -0.62 | — | The one genuine late-cycle crack; watch for follow-through |
| Initial jobless claims | 206,000 | → unchanged | Labor market intact; 30,500 below the alarm level |
The contradiction I will not paper over: credit and labor both say expansion; housing and the cycle clock say late. That is exactly what "two coordinates" means. I am not resolving it this week because the data has not resolved it.
Where Are We Heading?
| Scenario | Probability | vs. Last Week |
|---|---|---|
| Stagflation persists (status quo) | 49.3% | ↓ -0.1% |
| Hard Landing / Liquidity Crisis | 36.4% | → unchanged |
| Goldilocks (growth + disinflation) | 14.3% | ↑ +0.1% |
| Total | 100% |
The distribution barely moved, but the composition of the Goldilocks tail improved: the oil collapse is the first genuine input that supports it. One print is not a trend.
Trip wire status — all five, with distance to trigger:
| Trigger | Current | Distance |
|---|---|---|
| VIX > 35.0 for 3 consecutive days | 14.81 | Far — no fear priced |
| HY OAS > 5.0% | 2.68% | 232bp away |
| Weekly jobless claims > 236,500 | 206,000 | 30,500 away |
| NFCI > -0.429 | -0.56 | 0.13 away |
| MARY confirms shift to HARD_LANDING or LIQUIDITY_CRISIS | Not confirmed | — |
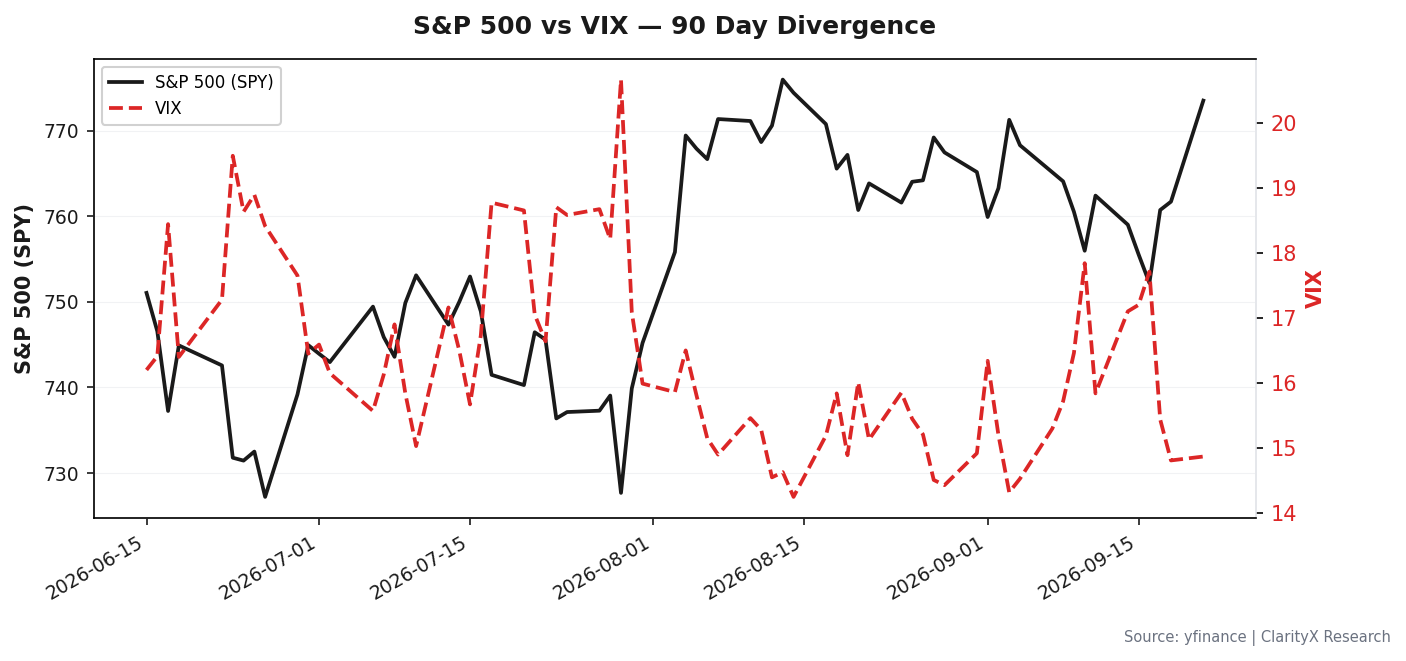
Zero critical, zero warning trip wires active. The board is quiet. Quiet is not safe — it is simply quiet.
What Does History Say?
Two analogs matter this week. The 2005–06 Housing Bubble Peak (83% similarity) is the closest match: quiet markets, tight credit, weakening permits — and the lesson is blunt: quiet markets don't mean safe markets. Watch SLOOS and permits for early cracks. We have the permits crack. We do not yet have the credit crack. The 2017–18 Goldilocks analog (80% similarity) is the bull case: S&P +30%, and the lesson is don't overthink it. The tension between these two analogs — one warning, one rewarding — is the same tension in the regime call. The third analog, the 2013 Taper Tantrum (56% similarity), reminds us that anticipation of tightening can be worse than tightening itself.
The Entry Question
Drawdown gauge: SPY is not in a meaningful drawdown from recent highs. There is no dip to buy and no panic to fade. The instinct to deploy now is not fear-driven — it is boredom-driven, which is worse.
Staged entry framework — do not skip stages:
- Stage 1 — VIX > 35.0 for 3 consecutive days. Current: 14.81. This is the fear gauge. When it spikes, the market is selling indiscriminately and quality is on sale. The fear is the signal. Action: deploy first tranche into quality equity.
- Stage 2 — High-Yield Option-Adjusted Spread > 5.0%. Current: 2.68%. This is the credit stress gauge. When junk spreads blow out, the selling is real and forced. Action: deploy second tranche.
"The instinct to buy the dip is strongest when the dip is only half done. Neither trigger is close. Patience is the position."
Sector Rotation & Strategy
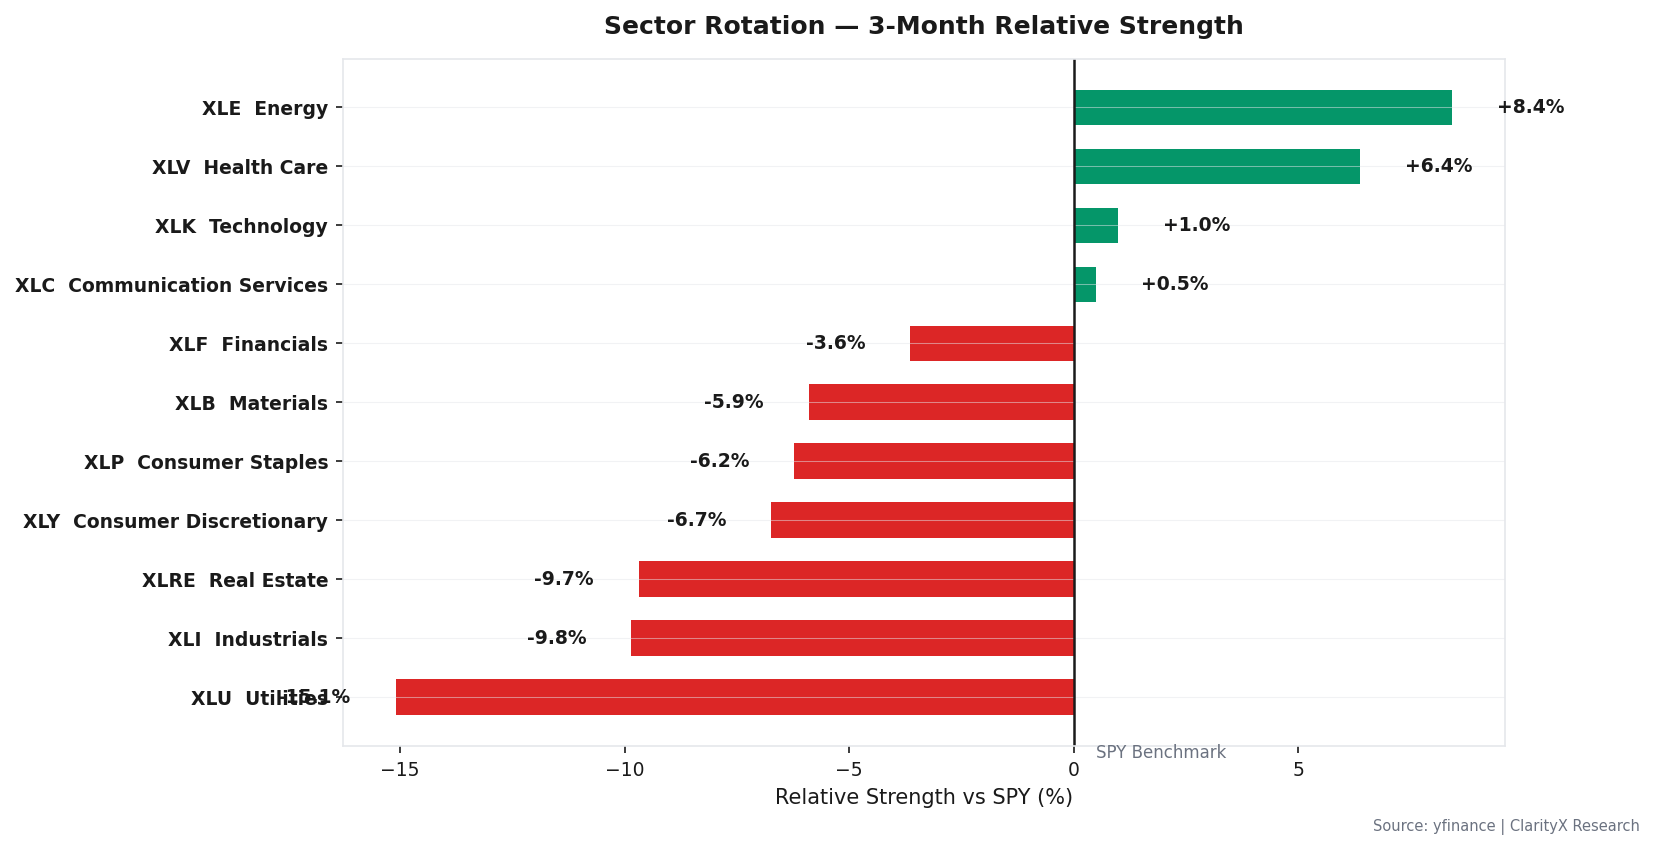
Relative strength this week favors energy-adjacent and quality names; the oil collapse is pressuring the commodity complex (commodities -3.27% over the trailing week per the report card). The validated strategy that fits this regime is Mean Reversion (STR-002 — VALIDATED, 8.54% CAGR, 0.39 Sharpe on Mag6, 2020–2024), which works best in range-bound, late-cycle markets — exactly the tape we have. Trend Following is validated for Goldilocks and Reflation, not here; its Sharpe is retracted pending a parity-confirmed backtest, so I am not citing a number.
The Portfolio
| Asset | Current Regime (Stagflation) | Target Regime (Goldilocks) | Recommended Now |
|---|---|---|---|
| Equity | 60% | 85% | 61% |
| Bonds | 6% | 3% | 1% |
| REITs | 2% | 6% | 2% |
| Commodities | 8% | 2% | 8% |
| Gold | 10% | 1% | 10% |
| TIPS | 6% | 1% | 6% |
| Int'l Bonds | 2% | 1% | 2% |
| Cash | 6% | 1% | 10% |
| Total | 100% | 100% | 100% |
Equity holds at 61% — the strategic anchor, tilted within to pricing-power and quality. Bonds are cut to 1% and cash raised to 10%, funding the real-asset ballast (commodities 8%, gold 10%, TIPS 6%) that does the inflation work nominal bonds cannot. The bridge: equity above 50% with a cautious macro read is not a contradiction — it is the SAA-holds-in-crisis posture. In stagflation, earnings can still grow with prices; selling equity locks in multiple compression without capturing the revenue. Time in the market, not timing it.
The Watch List
- VIX > 35.0 for 3 consecutive days → execute Stage 1 entry (current: 14.81)
- HY OAS > 5.0% → execute Stage 2 entry (current: 2.68%)
- Weekly jobless claims > 236,500 → tilt within equity to quality/low-vol; add bond-funded ballast (equity anchor holds)
- NFCI > -0.429 → tighten financial conditions flag
- MARY confirms shift to HARD_LANDING or LIQUIDITY_CRISIS → full crisis allocation
Options overlay: NO POSITION. VIX at 14.8 offers no fear setup and no greed setup. No transition signal = no edge. Stay patient.
Get this research delivered
New analysis, directly to your inbox. Research notifications only.